High-risk merchant account instant approval: Myths vs. reality
Providers advertise instant approval. Acquiring banks still run full underwriting. Here is what the term actually covers, who signs off on your account, and what happens after you go live.

Published August 30, 2026
AI Summary


In this article
What "instant approval" actually means
Who actually approves a high-risk merchant account
What happens between application and approval
Two myths worth correcting
Show More
Search for a way back into high-risk payment processing after a decline or an account closure, and one phrase dominates the results: instant approval. It speaks to what merchants worry about most, which is whether they will be approved at all, and how soon.
That reassurance is largely borrowed. Operationally, high-risk merchant account instant approval usually means an application has passed an automated front-end screen. Merchants read it as unrestricted processing and guaranteed acceptance. Those are not the same outcome. Instant approval is a fast entry into underwriting, never the end of it.
What "instant approval" actually means
Instant approval describes a moment early in the process. An application form has been accepted, identity checks have run, the business has been pre-qualified, or a provisional account record now exists.
None of that confirms guaranteed acceptance or immediate go-live. Manual website review, KYC and enhanced due diligence, and licence checks can all still sit ahead of you. Final limits, pricing, and conditions depend on the complete risk file and the acquiring institution's decision.
Four claims do most of the marketing work in this specialist category, and each one covers less ground than it appears to.
The claim | What it usually means | What merchants often hear |
|---|---|---|
Instant approval | Pre-screening has passed. KYB, bank approval, and integration remain open. | Processing goes live today. |
High acceptance | Broad appetite, subject to prohibited sectors, restricted countries, and licence requirements. | Every business is accepted. |
No credit check | No hard consumer credit inquiry. Bank statements, processing history, and compliance obligations still apply. | Nobody reviews my finances. |
Clean documents | Identity has been verified. | Risk has been accepted. |
The wording turns misleading when it never defines what is actually being approved: the application, the legal entity, or the entire processing flow.
Who actually approves a high-risk merchant account
The final decision usually rests with the acquiring bank or the regulated entity carrying settlement. A processor, payment facilitator, or broker may collect your documents, complete an initial review, and recommend terms. Accountability still sits with the acquirer.
That distinction explains something merchants find confusing. A provider's sales team can sound positive while the bank imposes conditions or declines the application outright. The two answer different questions. The acquirer has to decide whether the business is lawful and operationally acceptable, and whether it can absorb the loss if sales or chargebacks move against the forecast.
A single decision can pull in several teams:
- Underwriting.
- Fraud.
- AML.
- Compliance.
- Legal.
- Finance.
Some sectors also require senior risk approval before the file moves forward.
It explains one more thing. Approval from one provider proves little elsewhere, because each acquiring bank applies its own risk appetite.
What happens between application and approval
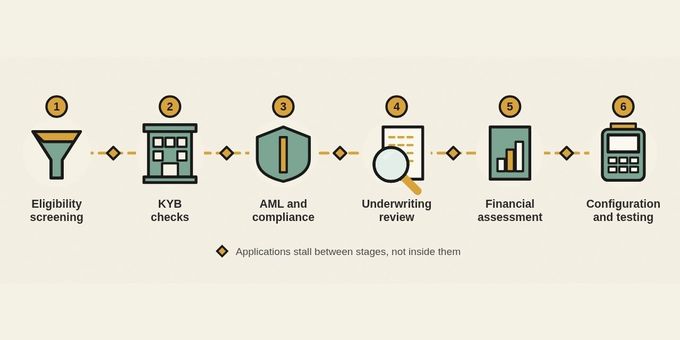
A high-risk application moves through several stages, and the account only goes live at the end of them.
- Eligibility screening. The sector, products, countries, and any prohibited activity.
- KYB checks. The company, its beneficial owners, and the bank account.
- AML and compliance review. The full business model, how it operates, and how the business was funded and maintained.
- Underwriting review. The website, billing model, policies, and licences.
- Financial assessment. Bank statements and processing history.
- Configuration and testing. Payment gateway, descriptor, currencies, fraud rules, and settlement settings.
Delays rarely come from the stages themselves. They come from what merchants submit. The most common causes are inconsistent documents, unclear ownership, undisclosed business models, missing licences, unrealistic forecasts, and a website that does not match the application. Every inconsistency creates delay, and delay has a way of snowballing.
Two myths worth correcting
Myth: Instant approval means everyone gets accepted
An automated system declines as quickly as it approves, so speed tells you nothing about the outcome.
Applications break down for predictable reasons. The activity may be prohibited outright, or the merchant category may sit outside the acquiring bank's appetite. Others fail because the business serves restricted jurisdictions without the required licences, ownership cannot be verified, or a previous processing relationship ended over AML enforcement or sanctions.
There is also a reason that has nothing to do with you. A bank may find your business perfectly acceptable and still decline, because it already holds too much exposure to your country, sector, or billing model.
Myth: No credit check means nobody looks at your finances
A hard inquiry on the owner's consumer credit file is one check among many, and skipping it changes very little.
Underwriters may still review business bank statements, source of funds and wealth, and processing history. They may also pull commercial credit reports, run identity screening, check company registries, and carry out sanctions and adverse-media searches.
Ask a better question. Not whether credit is checked, but which financial information will be reviewed, and whether any inquiry could affect your personal score. Weak liquidity still produces declines, lower processing limits, or stricter monitoring conditions further down the line.
Why requirements differ by industry
Each sector creates a different type of loss or compliance risk, and requirements diverge accordingly.
Adult services and content. Requirements go furthest where third parties upload content. Underwriters may review age and identity verification, performer consent, content moderation, and complaint handling. Geographic restrictions carry real weight. Adult merchant account instant approval cannot credibly mean approval without specialist review. At best, an initial screening has passed, and deeper checks on content governance, legal compliance, and retained evidence still follow.
Online trading. Regulated financial businesses raise licensing and customer-suitability questions that no automated screen can settle.
Subscription and recurring billing. Cancellation and renewal disputes drive the exposure, whatever sits behind the subscription.
A provider that promises instant approval without examining any of this is approving access to an application, not a sustainable acquiring relationship. The same logic applies to sectors this article does not cover, including online dating credit card processing and CBD payment processing.
Why a UK merchant should not assume a US claim applies
The UK and US operate under different regulatory, banking, and card-acquiring structures, so an approval claim written for one market may not describe the other.
Consideration | UK | US |
|---|---|---|
Who leads the decision | The acquirer or payment provider makes the decision within the applicable UK regulatory and card-scheme framework | The acquiring or sponsor bank and, where relevant, its payment facilitator determine approval under US law and card-scheme requirements |
Due diligence and permissions | KYB, beneficial-ownership and financial-crime checks apply, alongside any sector-specific permissions | KYB, beneficial-ownership and financial-crime checks also apply, with additional federal or state requirements depending on the activity |
Payment requirements | Strong Customer Authentication applies to many electronic payments, subject to exemptions | There is no direct nationwide equivalent to the UK SCA framework; applicable requirements vary by payment type, sector and state |
Approval in one country does not transfer. Account rejections and stricter contract terms follow different logic in each market, and the same structure and risk appetite may not be available to you. Before you apply, make any instant-approval claim identify the legal provider, the acquiring route, the jurisdictions covered, and any country-specific conditions.
Approval is not a one-time decision
Approval is not a verdict you keep. It is permission to process within an agreed risk profile, and that profile stays under review.
Ongoing exposure covers fraud and dispute monitoring under scheme frameworks like Mastercard's SMMP, plus sanctions screening, licence renewal, website reviews, and periodic KYB checks. Material changes trigger fresh underwriting: new products, new countries, ownership changes, or volume growth.
That last one catches people out. Legitimate growth can look suspicious if your actual processing no longer matches the application it was approved. The merchants who avoid trouble treat the underwriter as an ongoing stakeholder and disclose changes early, before transaction monitoring, periodic reviews or rising TC40 fraud reports reveal deteriorating performance or activity that no longer matches the approved risk profile.
Questions to ask before you sign
Durability matters more than speed, yet speed is what merchants compare first. Most energy goes into landing the first account, and almost none into how painful leaving it might be.
- Can stored customer payment tokens move to a new provider, or do they stay locked where they are?
- What is the process for releasing reserve funds once the relationship ends?
- Is there a realistic path to bringing a second acquirer on board?
- Who is the regulated provider, who is the acquirer, and who signs the agreement?
- Which sectors and countries is the account genuinely permitted to serve?
Then compare settlement timings, volume caps, refunds, and termination rights. Ask early, because recovering from a blacklisting is far harder than avoiding one. Write down the assumptions your approval was built on: expected volume, countries, and fulfilment timelines.
How Fibonatix approaches high-risk underwriting
Fibonatix works on the part of the timeline merchants can actually influence. That means preparing the right information and matching the business to a suitable acquiring route before full submission, then carrying it through documentation, integration, testing, and go-live.
Reliability comes from settling the merchant category, target markets, risk profile, compliance requirements, and operating model early. That reduces needless back-and-forth. It does not make bank underwriting disappear, and no provider can honestly claim otherwise.
The value is not easier approval at any cost. It is underwriting that matches how the business actually operates, plus support that continues after the account goes live.
Fibonatix (UK) Limited, company number 09738892, is authorised and regulated by the UK Financial Conduct Authority (FCA) as a Payment Institution (FRN 768776).
FAQs
What is high-risk merchant account instant approval?
It usually means an application has passed an automated front-end screen. The form was accepted, identity checks ran, or a provisional record was created. It does not confirm guaranteed acceptance, agreed limits, or live processing.
Who makes the final decision on a high-risk merchant account?
The acquiring bank or regulated entity carrying settlement. Processors, payment facilitators, and brokers collect documents and recommend terms, but the acquirer remains accountable. Underwriting, fraud, AML, compliance, legal, and finance teams can all contribute to one decision.
Does "no credit check" mean my finances are not reviewed?
No. It usually means no hard inquiry on the owner's consumer credit file. Business bank statements, source of funds, processing history, commercial credit reports, company registries, sanctions checks, and adverse-media searches can all still apply.
Can a high-risk merchant account be closed after it goes live?
Yes. Approval is permission to process within an agreed risk profile, and that stays under review. New products, new countries, ownership changes, or volume growth beyond the approved forecast can all trigger fresh underwriting or restrictions.